
✅ Current for tax year 2026
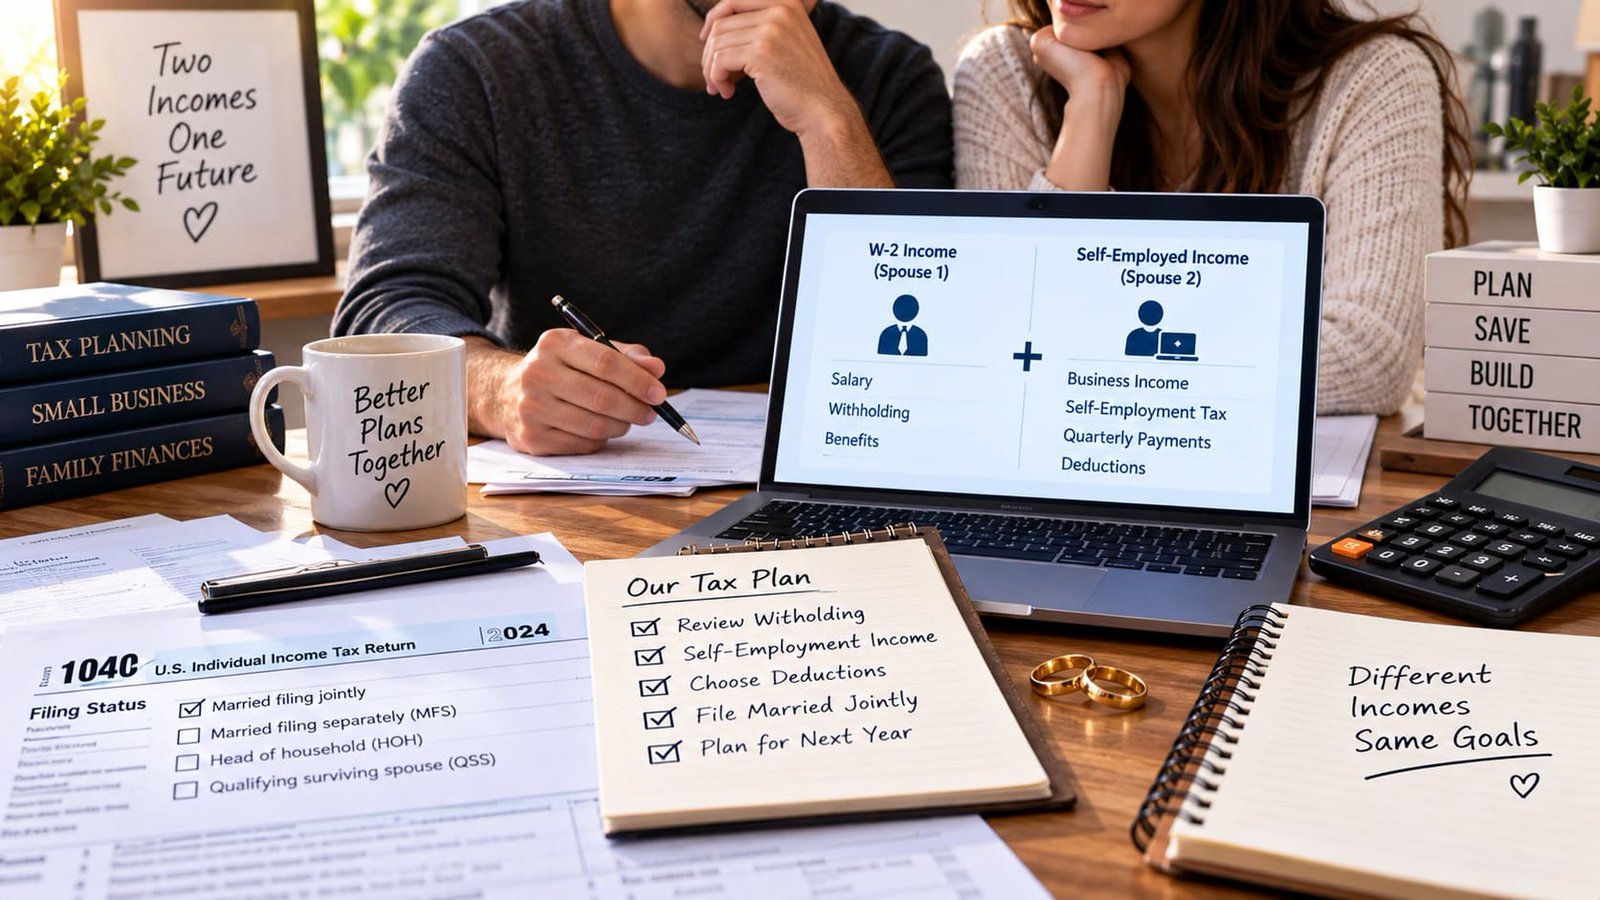
Quick answer: You have two real options — increase the W-2 spouse’s paycheck withholding to cover both incomes, or have the self-employed spouse pay quarterly estimates directly — and most mixed-income households end up combining a bit of both.
The core problem
When one spouse is a W-2 employee and the other is self-employed, the W-2 employer’s payroll withholding is calculated as if that paycheck were the household’s only income source. It has no idea a second, untaxed income stream exists. Without a deliberate fix, the couple files jointly in April and discovers the self-employed spouse’s income tax and self-employment tax were never actually paid in during the year — often alongside an underpayment penalty.
Option 1: increase the W-2 spouse’s withholding
The W-2 spouse can file an updated Form W-4 with their employer and use Step 4(c), “Extra withholding,” to add a flat additional dollar amount to each paycheck — enough, spread across the year’s pay periods, to cover the self-employed spouse’s estimated tax bill. This is often the simpler route for households that already have a working payroll relationship: one form, no separate quarterly deadlines to track, and withholding is generally treated by the IRS as paid evenly throughout the year regardless of when in the year it actually happened — which can help smooth out underpayment penalty calculations compared to lump quarterly payments.
Option 2: the self-employed spouse pays quarterly
The traditional route: the self-employed spouse estimates their income and self-employment tax liability and pays it directly via Form 1040-ES, four times a year. This keeps the two income streams cleanly separated and doesn’t require coordinating with an employer’s payroll department. Use the 1099 & Quarterly Tax Calculator to estimate each payment based on projected self-employment income, and see How to Calculate Quarterly Estimated Taxes for the full four-step process behind each one.
| Extra W-4 withholding | Quarterly estimates | |
|---|---|---|
| Who acts | W-2 spouse, one form | Self-employed spouse, four payments/year |
| Penalty treatment | Often treated as paid evenly all year | Tied to when each payment is actually made |
| Best when | W-2 income comfortably covers both tax bills | Self-employed income is the larger or more variable share |
A worked example
Suppose the self-employed spouse expects roughly $12,000 in combined income and self-employment tax for the year, and the W-2 spouse is paid biweekly (26 pay periods). Spread evenly, that’s about $460 in extra withholding per paycheck via Form W-4 Step 4(c) — a single form filed once, rather than four separate quarterly payments tracked throughout the year. If the self-employed spouse’s income is highly seasonal, though, this even-split approach can overpay early in the year and underpay later relative to when the income actually arrives — in that case, quarterly estimates paid as income comes in may track reality more closely.
Avoiding the underpayment penalty
The IRS generally won’t penalize you if, between withholding and estimated payments combined, you’ve paid in at least 90% of the current year’s tax or 100% (110% for higher earners) of last year’s total tax — whichever is smaller. This “safe harbor” is worth calculating deliberately rather than guessing, especially in a year where the self-employed spouse’s income jumped. The Take-Home Pay Calculator can help you see what’s actually landing in the household’s pocket after both incomes and both tax streams are accounted for.
What changes when income shifts mid-year
A withholding adjustment or quarterly estimate calculated for last year’s income won’t automatically catch up to this year’s — if the self-employed spouse’s income jumps or drops significantly partway through the year, revisit whichever method you’re using. For the W-4 route, that means filing an updated form with the new withholding amount; for quarterly estimates, it means recalculating the remaining payments rather than sticking to the original plan.
A hybrid approach
Many households land somewhere in between: a modest increase in W-2 withholding to cover a baseline, plus smaller quarterly payments from the self-employed spouse to true up the rest — particularly useful when the self-employed spouse’s income is too unpredictable to size a single flat withholding number confidently, but the household also doesn’t want to manage four full quarterly payments on its own.
What if both spouses are self-employed?
The strategies above assume one spouse has W-2 withholding to lean on, but plenty of households have two self-employed earners with no payroll withholding at all. In that case, both spouses generally need to make quarterly estimated payments, either as two separate calculations combined into one household total, or as one combined estimate covering both incomes. Filing one combined 1040-ES payment per quarter (rather than tracking two separate sets of payments) is often simpler for a jointly-filing household, as long as the total reflects both spouses’ combined tax liability accurately.
Recalculating after a major income change
A withholding adjustment or quarterly estimate is only as good as the projection behind it. If the self-employed spouse lands a major new client, loses one, or has a particularly strong or weak quarter, revisit the numbers rather than continuing on autopilot. For the W-4 route, this means submitting an updated form with a revised extra-withholding amount; for quarterly payments, it means adjusting the remaining quarters’ amounts rather than sticking to a January estimate that no longer reflects reality.
A note on state taxes
Everything above focuses on federal tax, but many states have their own withholding and estimated payment systems that work similarly — a W-2 spouse’s state withholding may also need adjusting, or the self-employed spouse may owe state quarterly estimates in parallel with federal ones. State rules vary significantly, so check your specific state’s requirements rather than assuming the federal approach automatically covers state obligations too.
How this decision interacts with other joint-filing choices
Married Filing Jointly is the default and usually most advantageous filing status for most couples, but it’s not automatic — some couples with significantly different income levels or certain deduction situations benefit from comparing against Married Filing Separately, even though that status generally carries a higher combined tax bill in most cases. If one spouse has substantial self-employment income and complicated deductions, it’s worth having a tax professional at least run the comparison once, even if the answer typically favors filing jointly, simply to confirm that’s genuinely the better choice for your specific numbers rather than assuming it by default.
Communication as much as calculation
Beyond the mechanics of withholding and quarterly payments, mixed-income households benefit from treating tax planning as an ongoing household conversation rather than a once-a-year task handled by whichever spouse “does the taxes.” The self-employed spouse typically has the clearest visibility into how their income is trending through the year, while the W-2 spouse controls the withholding lever — coordinating regularly, not just at tax time, is what actually keeps the numbers from drifting off track by December.
A checklist for the January planning conversation
Many mixed-income households find it useful to sit down once a year, ideally in January before the first quarterly deadline, and walk through the coming year deliberately together. Start with the self-employed spouse’s realistic income projection for the year, factoring in any known changes — a new client, a lost contract, a planned slowdown. From there, decide together whether the W-4 extra-withholding route, quarterly estimates, or a hybrid of both fits the household’s cash flow best this specific year, rather than defaulting to whatever was done last year without reconsidering whether it still fits.
It’s also worth using this same annual conversation to revisit whether the W-2 spouse’s own withholding is still accurate independent of the self-employed spouse’s situation — a raise, a bonus, or a change in the number of dependents claimed can all shift what the correct baseline withholding should be, and it’s easy for this to drift out of date over several years if it’s never revisited deliberately.
Bottom line
Mixed-income households have more flexibility than either spouse filing alone — use it deliberately. Whichever method you choose, revisit the numbers whenever the self-employed spouse’s income shifts meaningfully; a plan calculated once in January rarely holds up unchanged through December.
Related guides
- Schedule C, Line by Line: The Freelancer’s Walkthrough
- What Really Happens If You Forget to Report a 1099
- Can Gig Workers Claim the QBI Deduction Without an LLC or Sole Proprietorship?
- What Counts Toward Your AGI When You’re Self-Employed
- California Self-Employment Tax: What You Owe at the Federal and State Level
- Do You Pay Self-Employment Tax on Rental Income?
- How to Fill Out Form W-4 for 2026: A Situation-by-Situation Guide
- Child Tax Credit 2026: Who Qualifies, How Much You Get, and How the Phase-Out Works