
✅ Current for tax year 2026
Quick answer: MassHealth eligibility is based on your net self-employment income, not your gross revenue or a pay stub you don’t have — expect to submit your most recent Schedule C, along with recent documentation if your income has changed since you filed.
Program rules and accepted document types can be updated by MassHealth at any time — always confirm current requirements directly at mass.gov/masshealth or with the MassHealth Customer Service Center before submitting your application, and treat this guide as a starting framework rather than a substitute for the official checklist.
What counts as proof of self-employment income
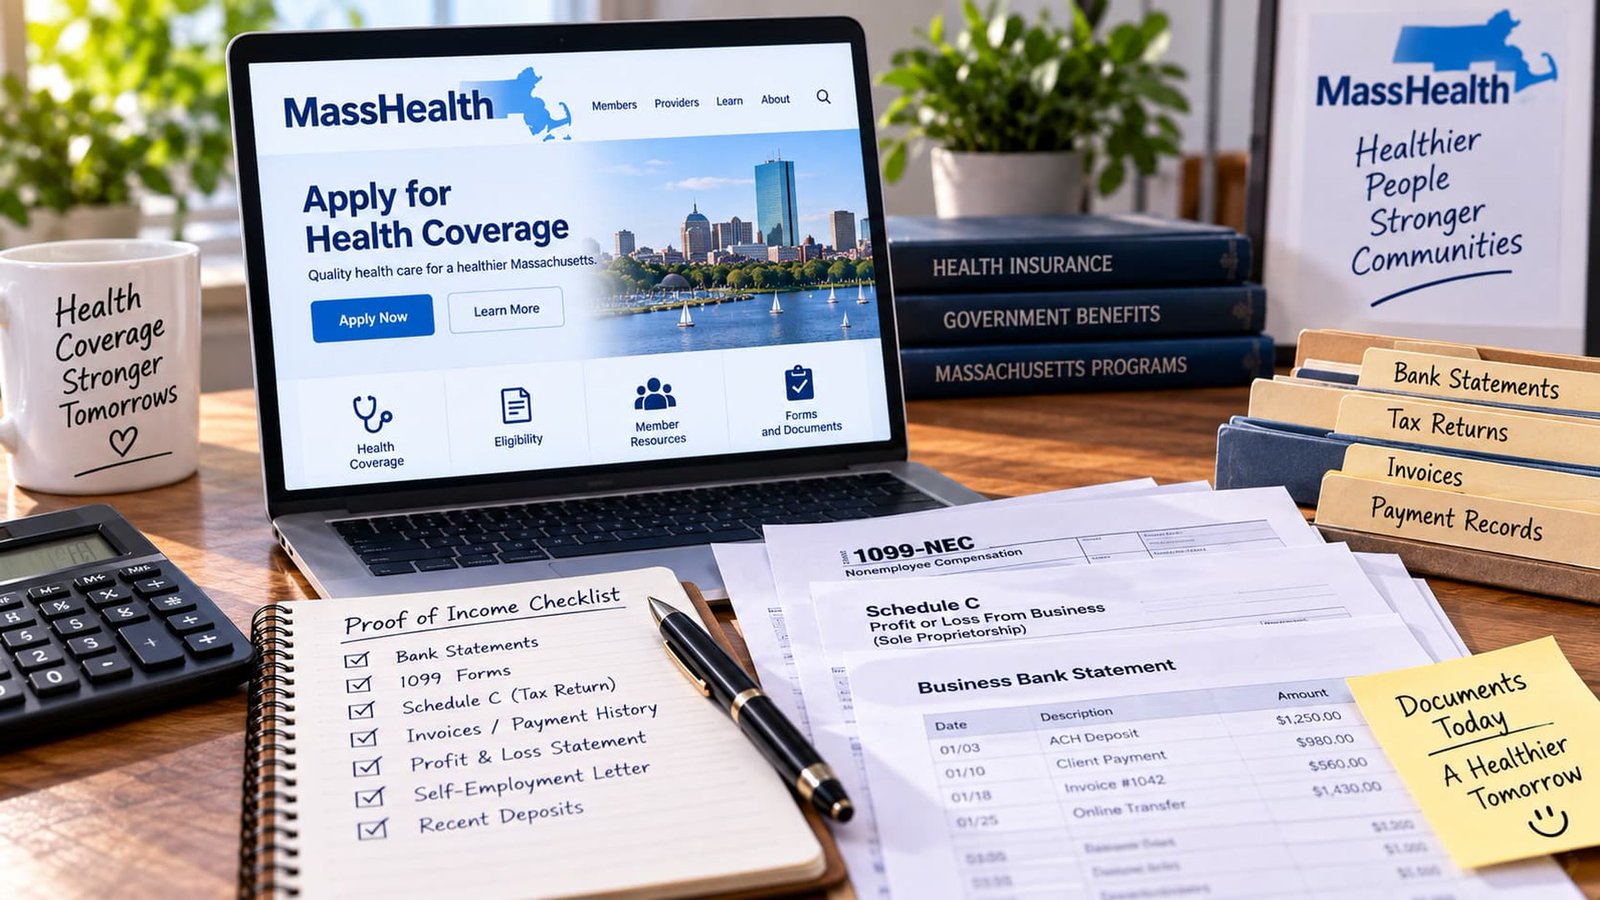
Unlike a W-2 employee who can submit recent pay stubs, self-employed applicants typically need to document income a different way. Commonly requested items include:
- Your most recently filed Schedule C (or Schedule C-EZ / relevant business return)
- A signed profit-and-loss statement covering the current year, if your income has changed since your last filed return
- Any 1099-NEC or 1099-K forms received from platforms or clients
- Bank statements showing business deposits, as supplementary evidence if requested
How MassHealth calculates your countable income
MassHealth generally uses a MAGI-based methodology similar to what’s used for ACA marketplace subsidies — meaning what counts is your net self-employment income (revenue minus allowable business expenses), not the gross amount that landed in your bank account. This is the same net profit figure that drives your Schedule C and your self-employment tax calculation — one accurate number that serves both your taxes and your benefits application, rather than two separate sets of math. See Affordable Health Insurance Options for the Self-Employed for how this same MAGI-based approach shows up again in ACA marketplace subsidy eligibility.
If your income is irregular
Gig and freelance income rarely arrives in even monthly amounts. If your most recent Schedule C doesn’t reflect your current earning pattern — say, income has dropped since you filed, or it fluctuates seasonally — MassHealth applications generally allow you to submit a current profit-and-loss statement or recent months of records instead of relying solely on last year’s return, along with a written explanation of the change. Keeping simple, consistent monthly records throughout the year makes this far easier when the request comes.
What happens if your application is questioned or denied
If MassHealth requests additional documentation or denies an application based on unclear or insufficient income proof, most determinations come with an appeal or reconsideration process, along with a specific timeframe to respond. Responding promptly with organized, clearly labeled documentation — rather than a disorganized folder of receipts — meaningfully improves how quickly a resubmission or appeal gets resolved. This is another place where consistent recordkeeping throughout the year, rather than reconstructed after the fact, pays off directly.
Recordkeeping habits that make this painless
- Reconcile business income against bank deposits monthly, not annually
- Keep a running profit-and-loss statement updated throughout the year, not just at tax time
- Save every 1099-NEC or 1099-K as it arrives, in one dedicated folder
- Note any significant income change (a lost client, a new platform, a slow season) with a brief written explanation as it happens
Where this connects to your taxes
The habit that makes a MassHealth application painless is the same habit that makes tax season painless: accurate, current bookkeeping. If you’re not confident your Schedule C reflects your actual current-year numbers, work through the line-by-line Schedule C walkthrough and use the Tax Deduction Calculator to make sure your net profit figure — the one every agency downstream will ask about — is right in the first place.
How this compares to proving income for other programs
MassHealth isn’t the only program that asks self-employed applicants to document income differently than W-2 employees — ACA marketplace subsidies, SNAP benefits, and many state-level assistance programs use a similar MAGI-based approach built around net self-employment income rather than gross revenue or pay stubs. See Affordable Health Insurance Options for the Self-Employed for how this same documentation challenge shows up again in ACA marketplace applications specifically. Once you’ve built clean, current bookkeeping for one of these programs, that same documentation generally transfers cleanly to the others.
What a strong profit-and-loss statement actually includes
- The specific date range it covers, clearly labeled
- Total gross income for the period, broken out by source if you have multiple clients or platforms
- Business expenses itemized by category, matching what you’d eventually report on Schedule C
- Net profit clearly calculated (income minus expenses)
- Your name, business name (if applicable), and the date the statement was prepared
A profit-and-loss statement doesn’t need to be complicated or professionally formatted to be accepted — accounting software can generate one automatically (see Best Accounting Software for Self-Employed Professionals), or a simple spreadsheet with these elements works just as well, as long as the numbers are accurate and the format is clear.
Timing your application around your tax filing
If you’re applying for MassHealth shortly after filing your taxes, your most recent Schedule C will likely be your strongest, most complete piece of documentation. If you’re applying mid-year, well after your last filed return, a current profit-and-loss statement becomes more important, since a year-old Schedule C may no longer reflect your actual current income — especially for gig and freelance workers whose income can shift considerably within a single year.
How eligibility redeterminations work over time
MassHealth eligibility isn’t a one-time determination — most enrollees go through periodic eligibility redeterminations, which means the proof-of-income process described above isn’t a single hurdle to clear once, but something you’ll likely repeat on a recurring basis for as long as you’re enrolled. Keeping your bookkeeping habits consistent year-round, rather than scrambling to reconstruct records each time a redetermination notice arrives, makes each subsequent renewal significantly less stressful than the first application was.
What to do if your circumstances change between applications
A significant life change — a new dependent, a change in household composition, a move to a different address, or a major shift in business structure — can affect your eligibility or benefit level outside of the normal redetermination cycle. MassHealth generally expects enrollees to report such changes proactively rather than waiting for the next scheduled review, and self-employed applicants specifically should treat a significant change in business income (a new major client, or the loss of one) as exactly this kind of reportable change, documented with the same profit-and-loss approach described above.
Common documentation mistakes self-employed applicants make
A few patterns come up repeatedly and slow down otherwise straightforward applications: submitting a profit-and-loss statement without a clear date range, mixing personal and business bank statements without distinguishing between them, or submitting a Schedule C from several years ago without noting that current income differs significantly. Each of these is easy to avoid with a small amount of upfront care — label every document clearly, keep business and personal statements visibly separate, and always note explicitly if current income differs from your most recently filed return.
Another frequent issue: submitting gross platform earnings (like a raw 1099-K total) without any accompanying expense documentation, which can make income look artificially high to a reviewer who doesn’t automatically know to subtract business costs. Pairing any gross income document with your expense records or a completed profit-and-loss statement prevents this kind of misunderstanding and speeds up review considerably.
Bottom line
Keep your Schedule C current, keep a simple profit-and-loss update ready if your income shifts mid-year, and confirm the exact current document list with MassHealth directly before you apply — the paperwork burden here is manageable once your bookkeeping habits are already solid for tax purposes.
Related guides
- Current Mortgage Rates for the Self-Employed in Essex County
- Independent Contractor Lawyer: When You Need One and What It Costs
- Mortgage Loans for Self-Employed: Requirements, Documents, and Bank Statement Options
- Solo 401(k) vs. SEP IRA: Which Is Better for Self-Employed Retirement?
- Business Insurance for Independent Contractors: What You Need and What It Costs
- Workers’ Comp for Self-Employed: Do You Actually Need It?