
✅ Current for tax year 2026
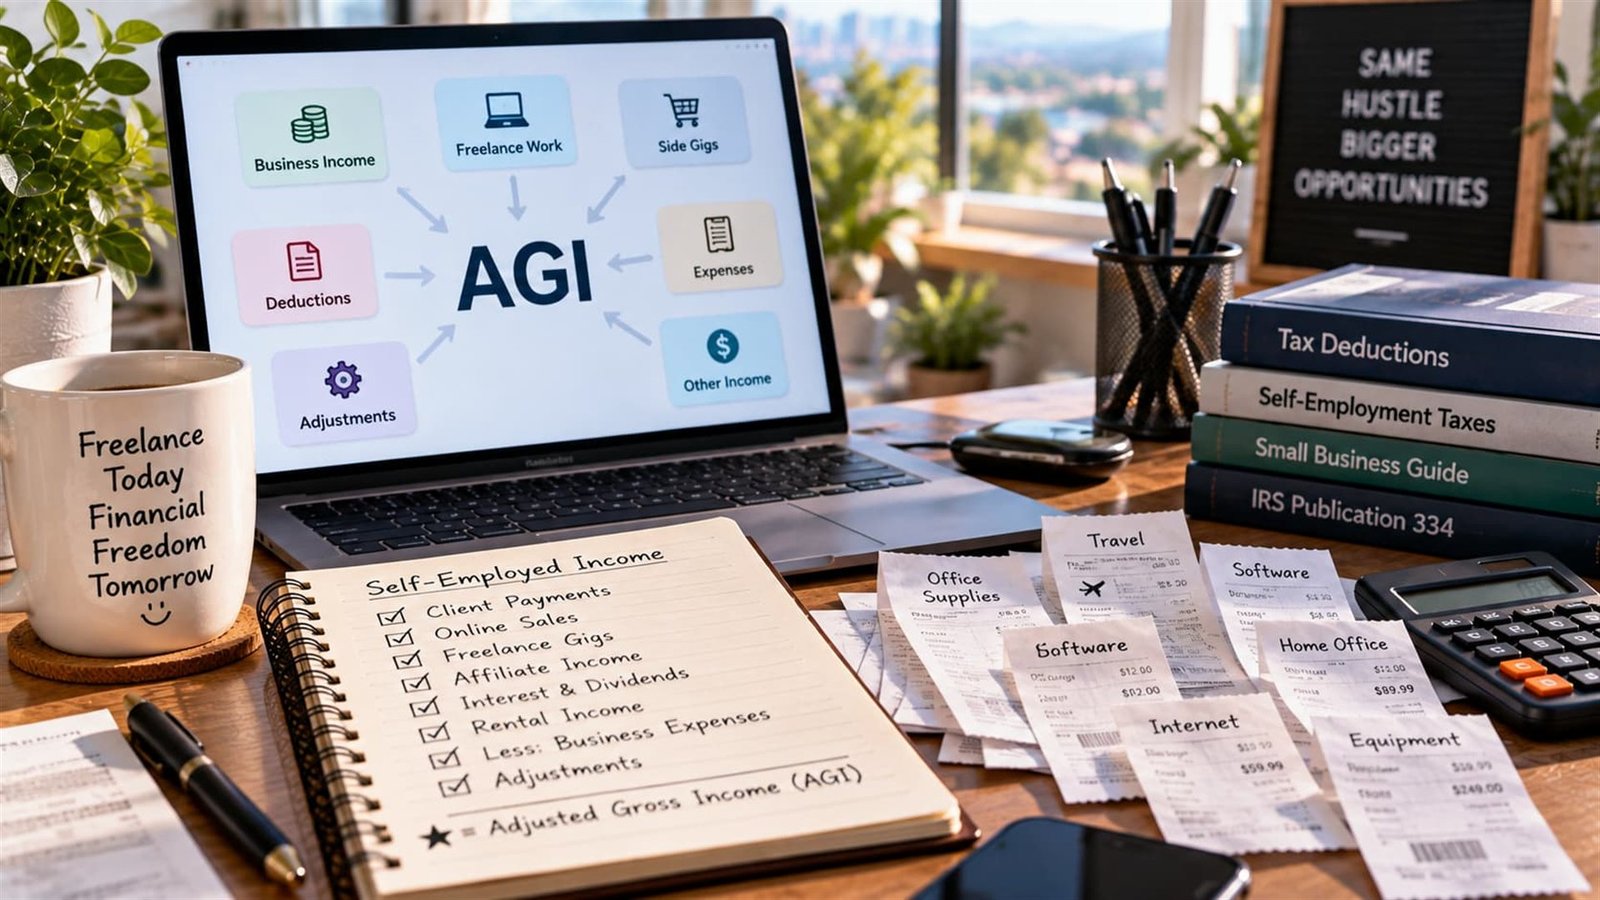
Quick answer: Your Adjusted Gross Income (AGI) isn’t your Schedule C net profit — it’s that number after a few more subtractions, most notably half your self-employment tax, your self-employed health insurance premiums, and any retirement contributions. AGI is usually meaningfully lower than your net profit, and it’s the figure that determines a lot more than just your tax bracket.
Why AGI matters beyond your tax bill
AGI (and its cousin, Modified AGI) is the gatekeeper number for a long list of things that have nothing to do with your tax rate directly: eligibility for certain deductions and credits, income-based phase-outs like the tips deduction, and even things like income-driven student loan payment calculations or ACA marketplace subsidy amounts. Two self-employed people with the same net profit can end up with different AGIs — and different eligibility for things — based on what else they subtract.
The path from net profit to AGI
Start with your Schedule C net profit. Subtract:
- The deductible half of your self-employment tax
- Your self-employed health insurance premiums, if you qualify
- Contributions to a SEP-IRA or Solo 401(k)
Add back any other income you have — W-2 wages, interest, dividends, rental income — and the total is your AGI. Notice that the Qualified Business Income deduction is not part of this calculation; it comes off AGI later, on the way to taxable income, not before.
A quick example
A freelancer nets $80,000 on Schedule C, pays $4,000 in half of their self-employment tax, $6,000 in health insurance premiums, and contributes $8,000 to a Solo 401(k). Their AGI is roughly $80,000 − $4,000 − $6,000 − $8,000 = $62,000, before any other income is added — nearly $18,000 lower than their net profit.
Where this leaves your tax calculation
Your self-employment tax is based on net profit directly, but your federal income tax is based on taxable income, which starts from AGI and subtracts the standard deduction (and QBI, separately). Our 1099 & quarterly tax calculator runs this full chain automatically once you enter your net income.
AGI vs. Modified AGI (MAGI)
AGI and MAGI aren’t the same number, and mixing them up leads to wrong eligibility estimates. AGI is the figure calculated exactly as described above. MAGI starts from AGI and adds back specific items depending on which benefit you’re checking — commonly, things like foreign earned income exclusions or certain IRA deduction add-backs. The catch: MAGI isn’t one universal number — the add-backs differ depending on whether you’re checking ACA marketplace subsidy eligibility, an IRA contribution limit, or a student loan repayment calculation. Two different programs can technically use two slightly different MAGI figures built from the same starting AGI. When a specific program’s eligibility matters, check that program’s own MAGI definition rather than assuming your AGI is the final answer.
Why this matters for phase-outs
Several valuable tax breaks shrink or disappear entirely above specific AGI or MAGI thresholds — the tips deduction discussed elsewhere on this site, IRA deduction limits when you’re covered by a retirement plan, and Child Tax Credit phase-outs among others. Because retirement contributions and self-employed health insurance both reduce AGI before these thresholds are checked, maximizing those deductions can sometimes pull a self-employed filer back under a phase-out line entirely — turning a partial deduction or credit back into a full one.
AGI and the standard deduction, together
AGI and the standard deduction are two separate steps that people sometimes collapse into one. AGI is calculated first — Schedule C net profit minus the specific adjustments described above. The standard deduction (or itemized deductions, if higher) is subtracted after that, from AGI, to arrive at taxable income — the actual number tax brackets apply to. A self-employed filer with $62,000 in AGI and the 2026 single standard deduction doesn’t pay tax on the full $62,000; they pay tax on $62,000 minus that standard deduction amount. Keeping this order straight matters because some limits and phase-outs are based specifically on AGI, before the standard deduction comes off, while your actual tax bracket is based on taxable income, after it does.
Why some people’s AGI is negative
In a genuine loss year — expenses exceeded income, or several adjustments stack up — it’s possible for AGI to be negative, sometimes called a net operating loss situation. This isn’t a paperwork error; it’s a real outcome for a business having a difficult year, or one making large deductible retirement contributions relative to a modest profit. A negative AGI typically means no federal income tax is owed for the year and can, in some circumstances, be carried forward to offset a future year’s income — a situation specific enough that it’s worth professional guidance rather than general reading.
Related guides
- California Self-Employment Tax: What You Owe at the Federal and State Level
- Can Gig Workers Claim the QBI Deduction Without an LLC or Sole Proprietorship?
- Do You Pay Self-Employment Tax on Rental Income?
- Schedule C, Line by Line: The Freelancer’s Walkthrough
- How to Avoid Self-Employment Tax Legally: 9 Strategies That Work
- Married Filing Jointly Tax Guide: How to Handle Withholding When One Spouse Is Self-Employed
- How Much Tax Do You Pay on a 401(k) or IRA Withdrawal? Worked Examples by Age
- Inherited 401(k) Taxes: The 10-Year Rule, RMDs, and What a Beneficiary Owes
- How Much Does a 401(k) Contribution Reduce Your Taxes? The Deduction Math With Examples
- Roth Conversion Taxes: How to Estimate the Bill and Report It on Form 8606
- Self-Employed Health Insurance Deduction (Form 7206): Who Qualifies and Where to Enter It
- Health Savings Account for the Self-Employed: 2026 Limits, Tax Savings, and HDHP Rules
- S Corp Tax Write-Offs: What You Can Deduct, Health Insurance, and the Accountable Plan
- Standard Deduction for 2025 and 2026, Including the Extra Amounts for Seniors
- Capital Gains Tax Rates for 2026: Thresholds, Short vs. Long Term, and Four Worked Examples
- Child Tax Credit 2026: Who Qualifies, How Much You Get, and How the Phase-Out Works
Sources
AGI calculation order follows the IRS’s official Form 1040 page and its Schedule 1 adjustments.