
✅ Current for tax year 2026
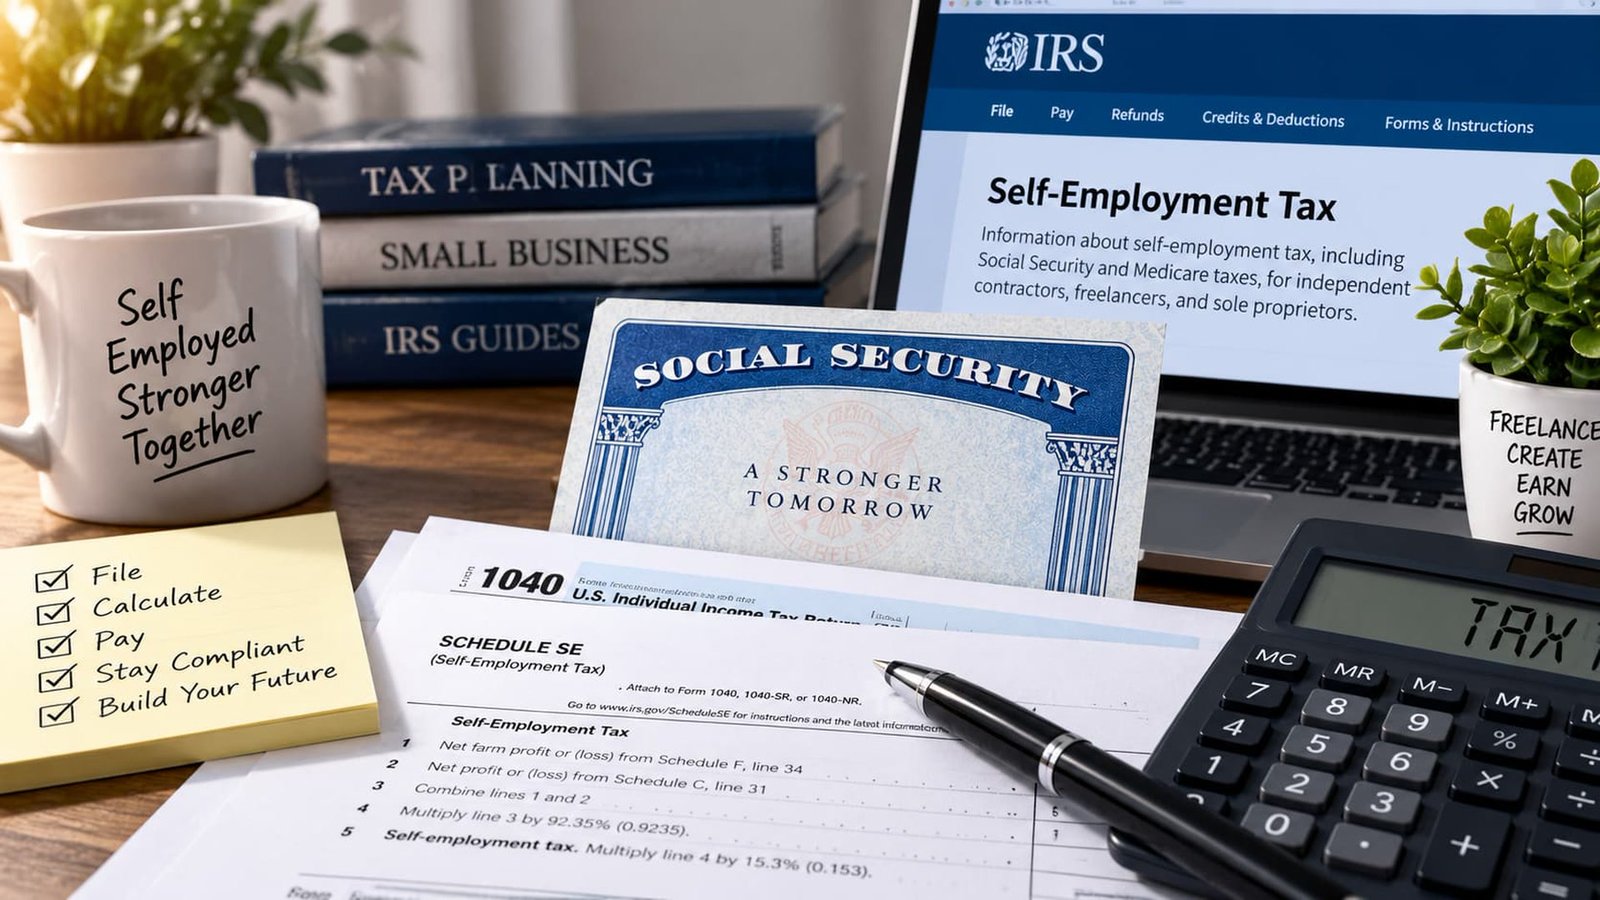
Quick answer: There’s no employer to withhold or match Social Security for you, so the IRS collects it through self-employment tax — 15.3% of your net self-employment earnings, paid in through quarterly estimates rather than a paycheck deduction.
What self-employment tax actually covers
Self-employment (SE) tax is your version of the FICA taxes a W-2 employee and their employer split. It has two parts: 12.4% for Social Security and 2.9% for Medicare, for a combined 15.3%. It’s calculated on Schedule SE and applies to 92.35% of your net profit from Schedule C — not your gross revenue, and not your full net profit. Run your numbers through the Self-Employment Tax Calculator to see this applied to your actual income instead of a generic example.
| Part | Rate | Applies to |
|---|---|---|
| Social Security | 12.4% | Net SE earnings up to the annual wage base |
| Medicare | 2.9% | All net SE earnings, no cap |
| Additional Medicare | 0.9% | Net SE earnings over $200,000 (single) / $250,000 (MFJ) |
Step-by-step: calculating what you owe
The math runs in a fixed order every year:
- Start with net profit from Schedule C, Line 31 — see the line-by-line Schedule C walkthrough if you haven’t filled it out yet.
- Multiply by 92.35%. This adjustment exists because a W-2 employee’s Social Security wage is reduced by the employer’s matching share before tax applies — this is the self-employed equivalent.
- Apply 12.4% to that adjusted amount, up to the Social Security wage base for the year (check ssa.gov for the current figure — it’s indexed for inflation annually).
- Apply 2.9% to the full adjusted amount, with no cap. Add the 0.9% Additional Medicare Tax if your combined earnings exceed the threshold for your filing status.
- Deduct half of your total SE tax as an adjustment to income on Schedule 1 — this is the one built-in break that offsets the “employer half” you’re effectively paying yourself.
The Tax Deduction Calculator can help you see how that deduction, plus your other write-offs, changes your actual taxable income before you get to this math.
A worked example
Say your net Schedule C profit for the year is $80,000. Multiply by 92.35% to get $73,880 in adjusted net earnings. The 12.4% Social Security portion applies to the full $73,880 as long as it’s under the annual wage base, coming to roughly $9,161. The 2.9% Medicare portion applies to the same $73,880 with no cap, adding roughly $2,143. Total self-employment tax: about $11,304 — of which half, roughly $5,652, comes back as an above-the-line deduction on your income tax return. This is exactly the kind of number that surprises first-year freelancers who only budgeted for income tax and forgot SE tax is a second, separate bill on top of it.
Where the wage base cap actually matters
The 12.4% Social Security portion only applies up to the annual wage base — once your adjusted net earnings exceed that threshold, the 12.4% stops accruing on the excess, though the 2.9% Medicare portion (and the 0.9% Additional Medicare Tax above the higher threshold) continues with no ceiling at all. This matters most for higher-earning self-employed individuals who also have W-2 income from a second job — Social Security withholding from that job counts toward the same annual cap, so it’s worth tracking combined earnings across both if you’re close to the threshold, to avoid overpaying.
Paying it throughout the year
Because nothing is withheld automatically, the IRS expects you to pay SE tax (plus income tax) as you earn it, through quarterly estimated payments on Form 1040-ES. Most self-employed people underestimate this the first year and get hit with an underpayment penalty on top of the tax itself.
- Q1 — April 15
- Q2 — June 15
- Q3 — September 15
- Q4 — January 15 of the following year
Use the 1099 & Quarterly Tax Calculator to estimate each payment instead of guessing — a rough quarterly number set aside as income arrives beats a lump-sum surprise every April. See How to Calculate Quarterly Estimated Taxes for the full step-by-step process behind each payment.
Common mistakes that make the bill bigger than it needs to be
- Forgetting the 92.35% adjustment and calculating 15.3% directly on full net profit — this overstates the tax owed.
- Not claiming the deductible half of SE tax on Schedule 1, which is easy to miss if you’re filing manually.
- Ignoring the Additional Medicare Tax threshold when income from multiple sources (a job plus self-employment) pushes combined earnings over the limit.
- Treating quarterly payments as optional in a strong income year, then facing both the tax and an underpayment penalty at once.
What this means for your retirement benefit
Every dollar of SE tax you pay is also building your Social Security earnings record — the benefit calculation the SSA uses when you eventually claim retirement benefits is based on your taxed earnings history, self-employment included. That’s separate from — and doesn’t replace — a private retirement account. If you’re also weighing a Solo 401(k) or SEP IRA, know that those contributions reduce your income tax but not your SE tax; the 15.3% still applies to your full net profit before retirement contributions come off.
How this differs if you also have a W-2 job
Plenty of self-employed people aren’t fully self-employed — they freelance alongside a regular job. In that case, your W-2 employer already withholds and matches Social Security on your wages, and that withholding counts toward the same annual wage base. If your combined W-2 wages and self-employment earnings push you over the threshold, you may end up overpaying the Social Security portion across both income sources, since your employer doesn’t know about your side income and calculates their withholding as if it were your only earnings. The good news: any excess Social Security tax withheld this way is refundable — it’s calculated and credited back to you when you file, so it’s not lost, just something to be aware of rather than a genuine loss.

Frequently confused terms
- Self-employment tax — the 15.3% combined Social Security and Medicare tax on net self-employment earnings, calculated on Schedule SE.
- Income tax — a completely separate calculation based on your total taxable income across all sources, at your marginal bracket, on Form 1040.
- Quarterly estimated tax payments — how you pay both of the above throughout the year, via Form 1040-ES, since nothing is withheld automatically.
- FICA tax — the employee/employer version of the same Social Security and Medicare taxes, split between a W-2 worker and their employer; self-employment tax is the self-employed equivalent, just paid entirely by you.
Why some new freelancers miscalculate this in year one
The single most common first-year mistake is budgeting only for income tax and forgetting self-employment tax is a completely separate 15.3% bill layered on top. Someone moving from a W-2 job might remember their old paycheck’s tax withholding rate and assume something similar applies here — but that old rate only ever reflected income tax and the employee half of FICA, with the employer’s half invisible to them the whole time. As a self-employed filer, you’re now responsible for both halves, which is precisely why the rate feels so much higher than what used to come out of a paycheck, even at a similar income level.
What happens at retirement age
The Social Security portion of self-employment tax isn’t just an expense — it’s building the earnings record the Social Security Administration uses to calculate your eventual retirement benefit, disability benefit, and survivor benefits for your family. The SSA generally looks at your highest-earning years across your working life, self-employment and W-2 years combined, to calculate that benefit. A stretch of years with little or no reported self-employment income — because income was underreported, or because deductions pushed net profit unusually low — can genuinely lower your future benefit calculation, which is one more reason accurate, honest reporting matters beyond just this year’s tax bill.
Bottom line
Self-employment tax isn’t optional and it isn’t withheld for you — it’s calculated on your net profit, paid quarterly, and half of it comes back as a deduction. Start with the Self-Employment Tax Calculator to see your actual number, then build a quarterly habit around it so it never becomes a surprise.
Related guides
- How to Avoid Self-Employment Tax Legally: 9 Strategies That Work
- Do You Pay Self-Employment Tax on Rental Income?
- California Self-Employment Tax: What You Owe at the Federal and State Level
- How Much Tax Do You Pay on a 401(k) or IRA Withdrawal? Worked Examples by Age
- Inherited 401(k) Taxes: The 10-Year Rule, RMDs, and What a Beneficiary Owes
- How Much Does a 401(k) Contribution Reduce Your Taxes? The Deduction Math With Examples
- Self-Employment Tax Optional Methods: When the Farm and Nonfarm Options Make Sense
- Do S Corp Owners Pay Self-Employment Tax? Reasonable Salary Rules and a Worked Example vs. LLC