
✅ Current for tax year 2026
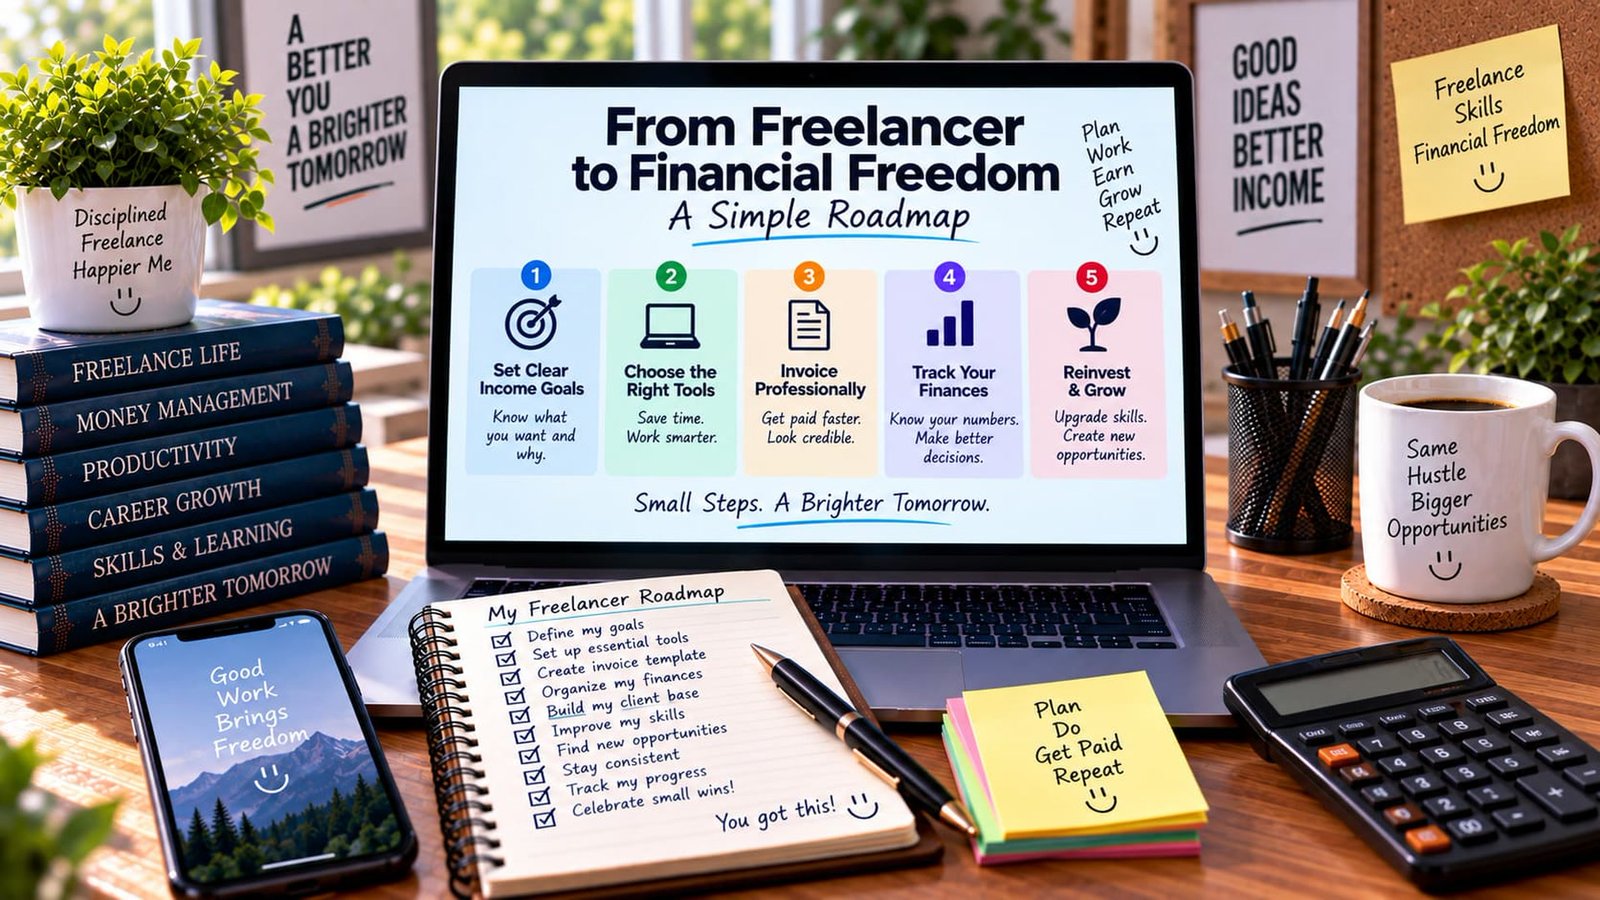
Quick answer: Build a financial runway and a client pipeline before you leave, then follow a simple five-step roadmap once you’re out: set clear income goals, choose the right tools, invoice professionally, track your finances, and reinvest to grow — while planning for the two structural changes that catch most new freelancers off guard: losing automatic payroll withholding, and replacing your employer-provided benefits.
Before you leave: build the runway
Most successful transitions happen gradually: freelancing on the side while still employed, building savings to cover several months of expenses, and lining up at least one or two committed clients before giving notice. A hard, unplanned jump from a steady paycheck to zero clients is the riskiest version of this transition, and it’s the version most likely to force rushed, underpriced decisions once you’re out.
Step 1: Set clear income goals
Know what you actually want and why — a specific monthly income target, not a vague “make enough to get by.” This single number should drive most of your early client and pricing decisions.
Step 2: Choose the right tools
Save time and work smarter from day one rather than cobbling together a workflow reactively. See Best Accounting Software for Self-Employed Professionals and The Best Invoicing Tools for the Self-Employed for where to start.
Step 3: Invoice professionally
Get paid faster and look credible from your very first client — a scrappy, informal invoicing process is one of the fastest ways to signal “still figuring this out” to a new client, right when you most need to project the opposite.
Step 4: Track your finances
Know your numbers and make better decisions with them — income, expenses, and the tax obligations that come with self-employment need to be visible to you continuously, not reconstructed once a year.
Step 5: Reinvest & grow
Upgrade your skills and create new opportunities with the income the business generates, rather than treating year one’s setup as the finished state. See 10 High-Paying Freelance Skills to Learn for Next Year for where that reinvestment might go.
- Define my income goals
- Set up essential tools
- Create an invoice template
- Organize my finances
- Build my client base
- Improve my skills continuously
- Find new opportunities
- Stay consistent through the slow months
- Track my progress
- Celebrate small wins along the way
The tax shift nobody warns you about
As an employee, taxes were withheld from every paycheck automatically — you never had to think about it. The moment you go self-employed, that stops entirely, and you become responsible for calculating and paying your own Social Security and Medicare tax plus income tax, in quarterly installments. Set up the 1099 & Quarterly Tax Calculator habit before your first freelance dollar arrives, not after your first tax bill surprises you — see How to Calculate Quarterly Estimated Taxes for the exact process.
Replacing your employer benefits
Health insurance and retirement contributions don’t disappear — they just become your responsibility to arrange. See Affordable Health Insurance Options for the Self-Employed for coverage options, and Solo 401(k) vs. SEP IRA for retirement accounts built specifically for people in your position.
The paperwork switch
You’ll go from a single W-2 each year to potentially several 1099s from different clients or platforms, all flowing into one Schedule C instead of a simple W-2 filing. It’s a real adjustment the first year, and it gets significantly easier once you’ve built the habit of tracking income and expenses as they happen.
How much runway is actually enough
While three to six months of expenses is a common guideline, the right number depends on how predictable your freelance income is likely to be. Someone transitioning with an existing client already lined up needs less runway than someone starting from zero with no pipeline. Someone in a field with long sales cycles (enterprise consulting, for example) generally needs more runway than someone in a field where work can be found relatively quickly (task-based gig work). Size your runway to your specific situation rather than a generic number.
Testing the waters before fully committing
A gradual transition — freelancing evenings and weekends while still employed, gradually reducing hours at a day job if your employer allows it, or negotiating a part-time arrangement during the transition — significantly reduces the risk compared to an abrupt full jump. This approach takes longer to reach full independence but validates that real client demand exists before your entire income depends on it.
The emotional adjustment, not just the financial one
Beyond the tax and benefits mechanics covered above, many new freelancers underestimate the psychological shift of losing a fixed schedule, regular colleague interaction, and the built-in validation of a manager’s feedback. This isn’t a reason to avoid freelancing, but it’s worth planning for deliberately — building in structure and social connection from day one rather than discovering the gap only after burnout sets in. See How to Prevent Burnout When You Are a Solopreneur for more on this specific challenge.
What to communicate to your employer during the transition
If you’re planning a gradual transition while still employed, review your current employment contract for any non-compete or moonlighting restrictions before taking on freelance work in the same field — some employers explicitly prohibit outside work in a competing capacity, and violating this can create real professional and legal risk. Being transparent with your employer where required, or at minimum understanding your specific contractual obligations, protects both your current job and your freelance transition from unnecessary complications.
Setting a realistic first-year income expectation
Most freelance transitions don’t immediately replace a prior salary — building a client base, refining your pricing, and establishing a reputation all take time, and a first year meaningfully below your prior W-2 income is common even for skilled professionals. Planning your runway and expectations around this reality, rather than assuming an immediate income match, reduces the financial pressure that causes many new freelancers to underprice their work out of short-term desperation.
What your first tax season as a freelancer will actually look like
The first tax season after transitioning from full-time employment to freelancing tends to be the most complex, since it often involves a partial-year W-2 combined with partial-year self-employment income, potentially different quarterly payment amounts for each part of the year, and reconciling withholding from the employment period against a full year’s actual tax liability. It’s genuinely worth working with a tax professional for this specific first transition year, even if you plan to handle your taxes independently in subsequent years once the pattern is more established and familiar.
Keep your final pay stub and any documentation of when exactly your employment ended, since this affects exactly how much was withheld before the transition and how much of the year’s tax liability the self-employment quarterly payments need to cover on their own.
Keeping a professional network active during the transition
It’s easy for a new freelancer to lose touch with former colleagues and industry contacts once the daily structure of an office environment disappears, but this network is often the single most valuable source of referrals and future client relationships. Deliberately maintaining these connections — periodic check-ins, staying visible on professional platforms, attending industry events — pays dividends well beyond the initial transition period, long after the novelty of freelancing has worn off.
Bottom line
The freedom of freelancing is real, but so is the loss of automatic withholding and employer benefits — plan for both deliberately in the months before you leave, and lean on the five-step roadmap above once you’re out, rather than improvising the whole structure from scratch.
Related guides
- Can Sole Proprietors Have Employees? What You Need to Hire Legally
- Independent Contractor Lawyer: When You Need One and What It Costs
- LLC vs. Sole Proprietorship: Which Is Best for Freelancers?
- Sole Proprietorship vs. Independent Contractor: What Is the Difference for Tax Purposes?
- Independent Contractor Payroll Software: How to Pay, Manage, and Report 1099 Workers
- Digital Nomad Visa Requirements: The Easiest Countries to Move To
- How to Set Firm Boundaries with Freelance Clients (Without Losing Them)
- How to Fill Out Form W-4 for 2026: A Situation-by-Situation Guide