
✅ Current for tax year 2026
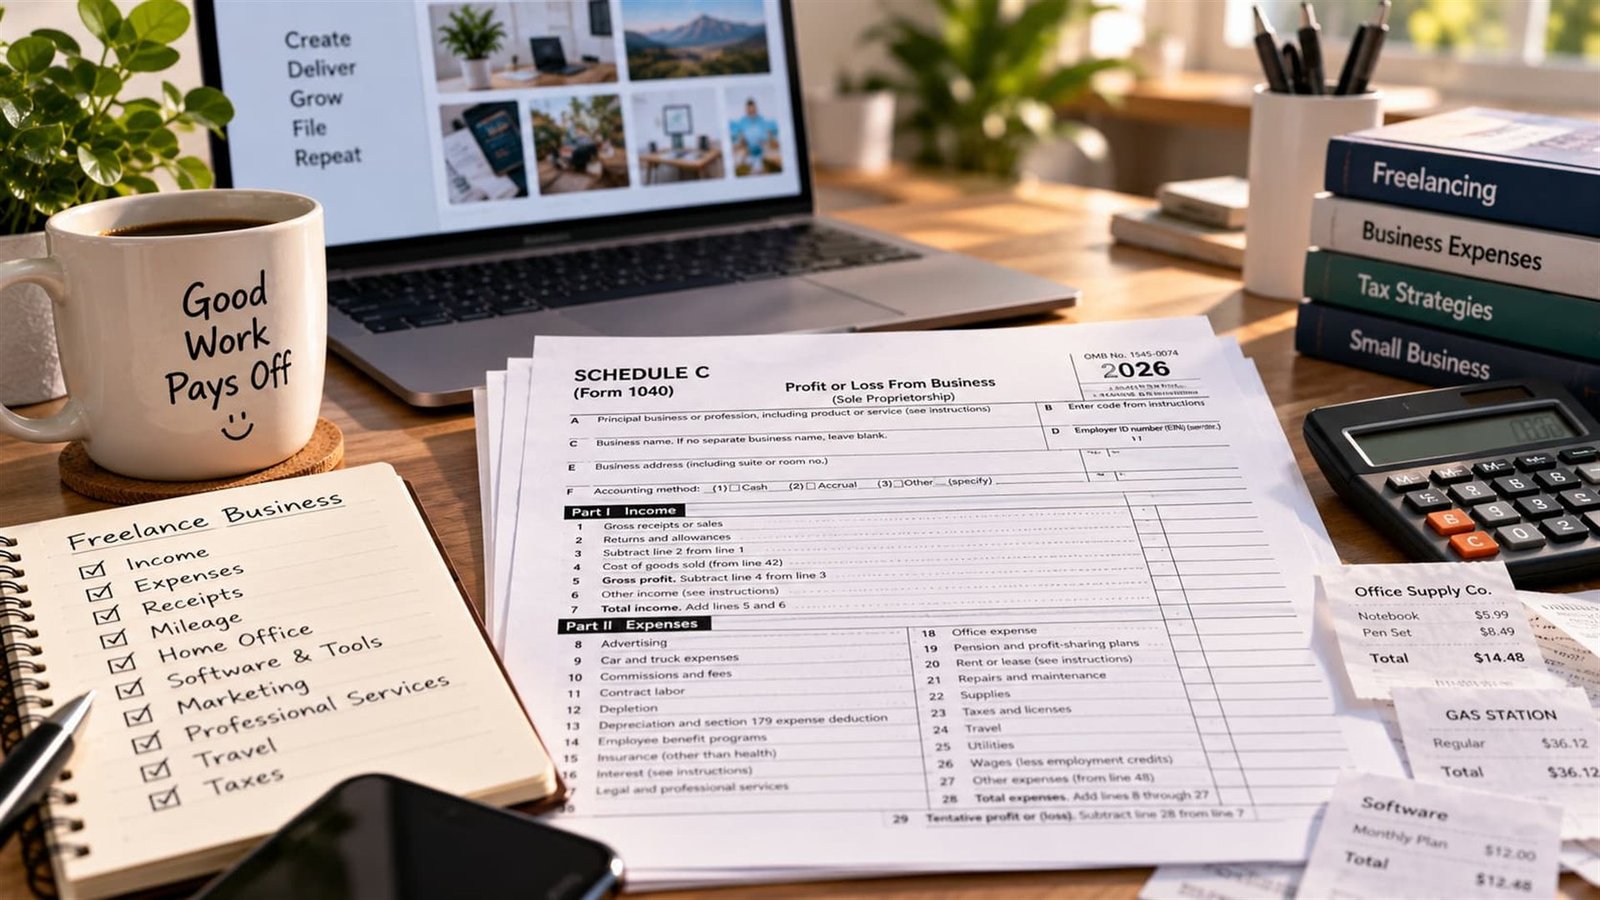
Quick answer: Schedule C is where every 1099 contractor and freelancer reports business income and expenses to the IRS. It has five parts — income, expenses, cost of goods sold, vehicle information, and other expenses — and the bottom line feeds directly into your self-employment tax and income tax.
Part I: Income
This is your gross receipts — everything you were paid before any expenses come off. If you have 1099-NEC or 1099-K forms, their totals (plus any income you received without a form) go here. This section also has a line for returns and allowances and a separate cost-of-goods-sold figure if you sell physical products, which get subtracted to reach your gross profit.
Part II: Expenses
This is the heart of the form — a long list of specific expense categories: advertising, car and truck expenses, insurance, legal and professional services, office expense, supplies, travel, utilities, and more, each with its own line. Instead of one big “expenses” number, the IRS wants your costs sorted by category. See our full deductions list for what typically fits where. Subtracting total expenses from gross profit gives you your net profit or loss — the number that matters most on this whole form.
Part III: Cost of Goods Sold
Only relevant if you sell physical products. This section calculates what your inventory actually cost you, which is subtracted in Part I rather than treated as a normal expense. Service-based freelancers and gig workers usually skip this section entirely.
Part IV: Information on Your Vehicle
If you claimed a vehicle expense in Part II, this section asks for details — total miles driven, business miles, and whether you have written evidence to support it. This is exactly why a contemporaneous mileage log matters: this section is asking you to confirm one exists.
Part V: Other Expenses
A catch-all for legitimate business costs that don’t fit any category in Part II — things like a specific subscription, a one-off business license fee, or bank charges on a business account. These get itemized and totaled, then folded into your total expenses in Part II.
Where the net profit number goes next
Your Schedule C net profit is the figure that determines your self-employment tax and flows into your federal income tax calculation. Plug it into the 1099 & quarterly tax calculator to see both numbers and a suggested quarterly payment.
A full example, start to finish
Take a freelance graphic designer with $52,000 in combined 1099-NEC income (Part I gross receipts). In Part II, they claim $2,400 in software subscriptions, $1,800 in a home office deduction, $1,200 for a new laptop and monitor, $900 in business insurance, and $600 in professional development — $6,900 in total expenses. That leaves a net profit of $45,100 (Part I minus Part II), skipping Part III entirely since they sell a service, not physical products. They didn’t use a vehicle for business this year, so Part IV is blank. A single $200 payment processing fee that didn’t fit any category in Part II gets itemized in Part V and folded back into the expense total. Their final net profit — $45,100 — is what flows to Schedule SE for self-employment tax and onto Form 1040 for income tax.
Do you need to file Schedule C if you had a loss?
Yes — a net loss on Schedule C still gets reported, and it isn’t just paperwork for its own sake. A business loss can offset other income on your return (W-2 wages, a spouse’s income on a joint return, investment income), potentially lowering your overall tax bill for the year. There’s a limit to be aware of: the IRS expects a business to be run with a genuine profit motive, and consistent losses year after year with no realistic path to profitability can eventually trigger a “hobby loss” review, where the IRS questions whether the activity is really a business at all. An occasional loss year is normal and expected; a pattern of losses stretching many years in a row is what draws scrutiny.
Related guides
- Can Gig Workers Claim the QBI Deduction Without an LLC or Sole Proprietorship?
- Married Filing Jointly Tax Guide: How to Handle Withholding When One Spouse Is Self-Employed
- What Counts Toward Your AGI When You’re Self-Employed
- What Really Happens If You Forget to Report a 1099
- California Self-Employment Tax: What You Owe at the Federal and State Level
- Do You Pay Self-Employment Tax on Rental Income?
- Freelance Writer Tax Deductions: The Complete Write-Off List for 1099 Writers
- Freelance Graphic Designer Tax Deductions: Software, Hardware, and Home Studio Costs
- Freelance Web Developer and Web Designer Tax Deductions: Software, Hosting, Coworking, and Gear
- Freelance Photographer Tax Write-Offs: Gear, Depreciation, Travel, and Studio Costs
- Hair Stylist Tax Write-Offs: Booth Rent vs. Commission, Supplies, and Licenses
- Tax Deductions Freelancers Often Miss: 27 Overlooked Write-Offs for 2026
- Home Office Deduction for Freelancers: Simplified vs. Actual Method (and Why Your Home's Value Doesn't Matter)
- Do You Need Receipts for Tax Write-Offs? What the IRS Accepts and How Long to Keep Records
- How to Write Off a Computer, Laptop, or Camera: Section 179, De Minimis Safe Harbor, or Depreciation
- Free Expense Tracker Template for Schedule C (Excel and Google Sheets)
- Mileage Log Requirements: What the IRS Wants and the Best Ways to Track It
Sources
Structure described follows the IRS’s official Schedule C (Form 1040) page.