
✅ Current for tax year 2026
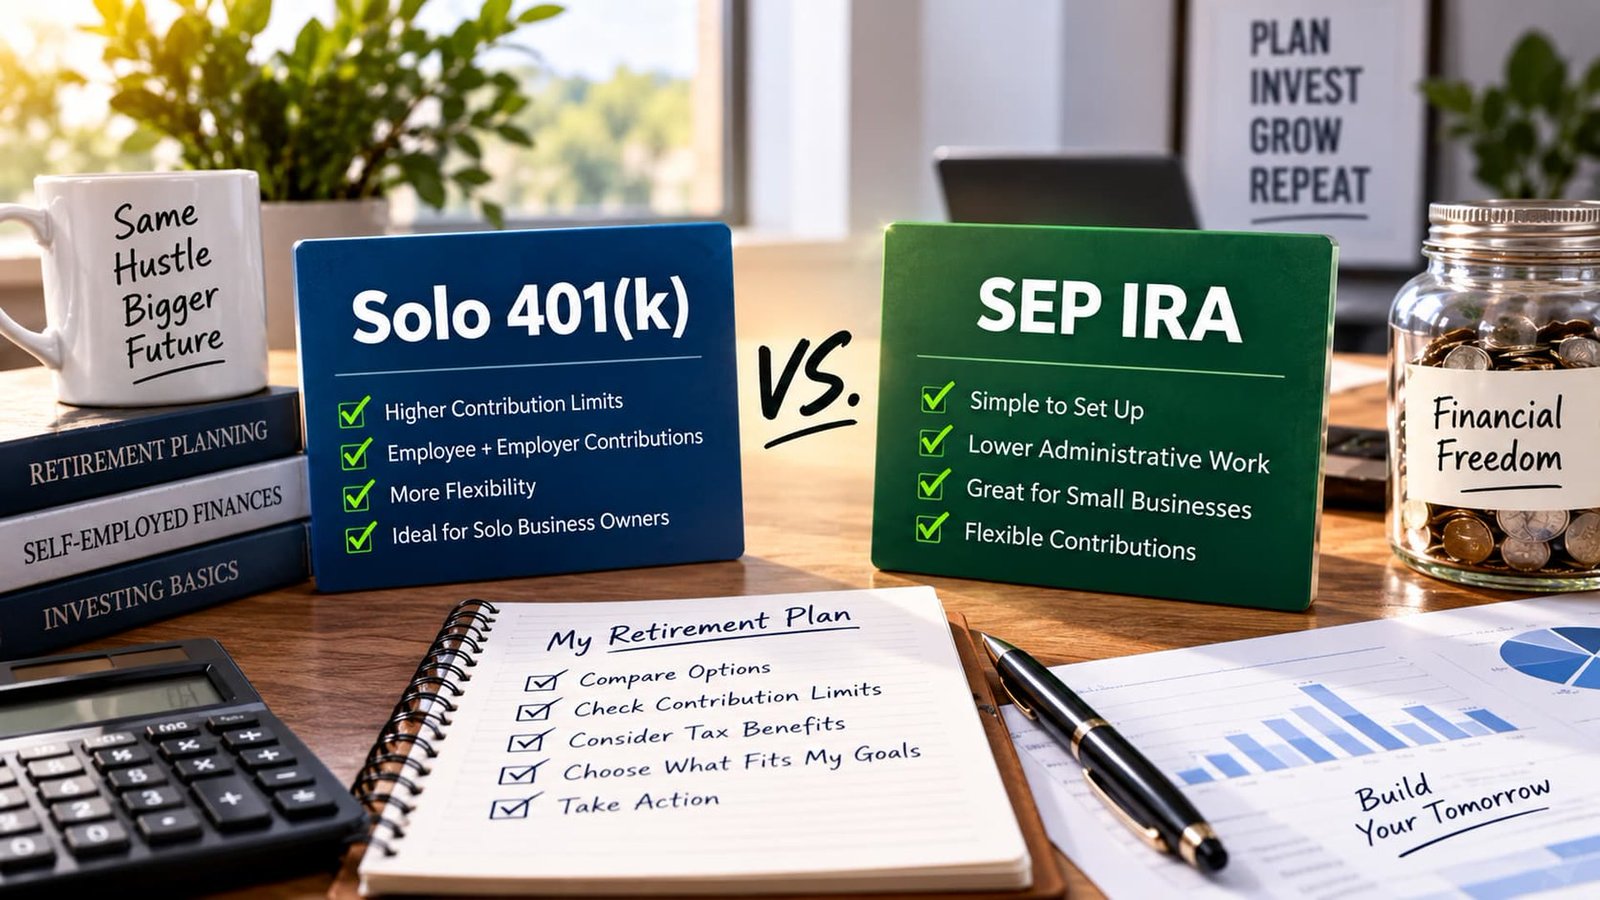
Quick answer: Both let you shelter a large slice of self-employment income from current income tax, but they build up contribution room differently — and for most solo operators under roughly six figures in net profit, that difference favors the Solo 401(k).
How a Solo 401(k) works
A Solo 401(k) — sometimes called a one-participant 401(k) — lets you contribute in two roles at once: as the “employee” of your own business, and as the “employer.” The employee side is an elective deferral, a fixed dollar limit that applies no matter how much your business actually earned. The employer side is a profit-sharing contribution, calculated as a percentage of your net self-employment earnings. Run your net profit through the Self-Employment Tax Calculator first — both your SE tax and your retirement contribution room are based on that same adjusted number.
How a SEP IRA works
A SEP IRA is simpler on paper: there’s no employee deferral at all, only an employer contribution, capped at a percentage of your net self-employment earnings (the same 20%-of-adjusted-net-profit math that applies to the Solo 401(k)’s employer side). No separate election, no plan document to file with the IRS each year once assets cross a certain threshold, no loan provision, and — with most custodians — no Roth option.
| Solo 401(k) | SEP IRA | |
|---|---|---|
| Contribution types | Employee deferral + employer profit-share | Employer profit-share only |
| Roth option | Usually yes | Rarely offered |
| Catch-up contributions (50+) | Yes | No |
| Loan option | Often yes | No |
| Setup deadline | Must be opened by Dec 31 | Can open and fund up to the tax filing deadline |
| Best for | Lower-to-mid net profit, want Roth or a loan option | Simplicity, or deciding to save after year-end |
Where they really differ at lower income
The employer-side math is identical between the two plans, so at low-to-moderate net profit the Solo 401(k) almost always allows a bigger total contribution, because the employee deferral isn’t tied to a percentage of earnings — you can defer up to the annual employee limit even in a year with modest profit. A SEP IRA only ever gives you the percentage-of-profit figure, so it takes considerably more net income before the two plans land on the same contribution room. See the worked example in Solo 401(k) Contributions: Employee or Employer? for the actual split.
A concrete comparison
Consider two freelancers, each with $50,000 in net self-employment earnings after the SE tax adjustment. Through a SEP IRA, both are limited to roughly 20% of that figure — about $10,000. Through a Solo 401(k), the same freelancer can defer a meaningful fixed amount as an employee (regardless of the $50,000 figure, up to the annual limit) plus the same roughly $10,000 employer contribution — often nearly doubling total contribution room at this income level. That gap narrows considerably as net profit climbs into six figures, which is exactly why the SEP IRA becomes more competitive for higher earners.
Paperwork and deadlines
This is the SEP IRA’s real advantage: you can open the account and fund it any time up until your tax filing deadline (including extensions), which makes it the right fallback if you’re deciding on retirement savings after the year is already over. A Solo 401(k) has to be established by December 31 of the year you want to contribute for — the employee deferral election specifically has to happen before year-end, even though you can technically fund it later. If you’re filing Schedule C for the first time and reading this in the following spring, that deadline may have already closed a Solo 401(k) door for last year. See the Schedule C walkthrough for where net profit — the number both plans are based on — actually comes from.
What happens if your income is unpredictable
Both plans handle a variable-income year reasonably well, but differently. With a SEP IRA, you simply contribute less (or nothing) in a lean year, with no ongoing obligation. With a Solo 401(k), the employer side works the same way, but the employee deferral is a separate decision each year — some freelancers pause it entirely in a tight cash-flow year and rely on the employer side alone, which is a completely valid approach and effectively turns the plan into something closer to a SEP IRA for that year.
Which one should you pick?
If you want to defer income regardless of how the year goes, want a Roth option, or think you might ever want to borrow against the balance, the Solo 401(k) is the stronger default. If you want the lowest-maintenance plan possible, or you’re deciding this in March instead of December, the SEP IRA covers you. Either way, the Tax Deduction Calculator can show how the resulting deduction changes your overall tax picture for the year.
What happens to each plan if your business slows down
A slow year affects the two plans differently. With a SEP IRA, a lean year simply means a smaller (or zero) contribution — there’s no ongoing commitment or penalty for skipping a year entirely. A Solo 401(k) behaves the same way on its employer side, but if you’ve been making regular employee deferrals through payroll-style contributions, you’ll want to actively pause or reduce those elections rather than assuming they stop automatically — most plans require you to update your deferral election directly rather than inferring it from a bad month.
Administrative costs to factor in
SEP IRAs are typically free or very low-cost to open and maintain through most major brokerages, with essentially no ongoing paperwork. Solo 401(k)s vary more by provider — some are free, some charge modest annual fees, and once plan assets cross a certain threshold (a figure that’s adjusted periodically), the IRS requires an annual Form 5500-EZ filing that a SEP IRA never requires. This isn’t a reason to avoid a Solo 401(k), but it’s a real difference in ongoing complexity worth knowing about before you commit, especially if you value minimal paperwork over maximum contribution room.
Can you have both at once?
Generally, no — you wouldn’t typically run a SEP IRA and a Solo 401(k) simultaneously for the same self-employment income, since the employer-side contribution room is shared across whichever plans you use for that business. Freelancers occasionally have both types of accounts if they have separate income streams or a prior-employer plan, but for a single sole proprietorship, picking one primary retirement vehicle keeps the contribution math straightforward and avoids the risk of accidentally overcontributing across the two.
How required minimum distributions work for each
Both account types are subject to required minimum distributions (RMDs) once you reach the applicable age, meaning the IRS eventually requires you to start withdrawing (and paying tax on, if traditional) a minimum amount each year. This is identical between a Solo 401(k) and a SEP IRA in broad strokes, though a Roth Solo 401(k) balance may have different RMD treatment than a Roth IRA depending on current rules — another point worth confirming with a tax professional as retirement age approaches rather than assuming the two account types behave identically in every respect. Neither plan is meaningfully better than the other purely on this dimension; it’s a secondary consideration behind contribution room and flexibility during your working years.
What to do if you’re not sure how much you’ll earn this year
Uncertainty about full-year earnings is normal, especially in a first or second year of self-employment. Rather than waiting until you have a precise number, many freelancers set a conservative recurring contribution early in the year and increase it once income becomes clearer — this is easier to do with a Solo 401(k)’s ongoing employee deferral than with a SEP IRA, which is typically funded in one or two larger contributions closer to your tax filing deadline once your actual net profit is known. If your income genuinely can’t be estimated with any confidence, the SEP IRA’s later funding deadline is a real practical advantage, letting the decision wait until your Schedule C numbers are final.
Bottom line
Neither plan is objectively better — they optimize for different things. The Solo 401(k) optimizes for maximum contribution room and flexibility at lower-to-mid income; the SEP IRA optimizes for simplicity and a later decision deadline. Both beat not saving at all, and both can be opened well before you need to decide exactly how much to contribute.
Related guides
- Take-Home Pay Calculator
- How to Avoid Self-Employment Tax Legally: 9 Strategies That Work
- What Counts Toward Your AGI When You’re Self-Employed
- Self-Employed Tax Deductions: The Complete List for 2026
- Can Gig Workers Claim the QBI Deduction Without an LLC or Sole Proprietorship?
- How Much Tax Do You Pay on a 401(k) or IRA Withdrawal? Worked Examples by Age
- Inherited 401(k) Taxes: The 10-Year Rule, RMDs, and What a Beneficiary Owes
- How Much Does a 401(k) Contribution Reduce Your Taxes? The Deduction Math With Examples
- Roth Conversion Taxes: How to Estimate the Bill and Report It on Form 8606
- Self-Employed Health Insurance Deduction (Form 7206): Who Qualifies and Where to Enter It
- Health Savings Account for the Self-Employed: 2026 Limits, Tax Savings, and HDHP Rules
- S Corp Tax Write-Offs: What You Can Deduct, Health Insurance, and the Accountable Plan