
✅ Current for tax year 2026
Quick answer: You’re allowed to contribute in both roles in the same year, and for most solo business owners, maxing the employee side first and treating the employer side as a bonus once profit is known is the more flexible order.
The employee side
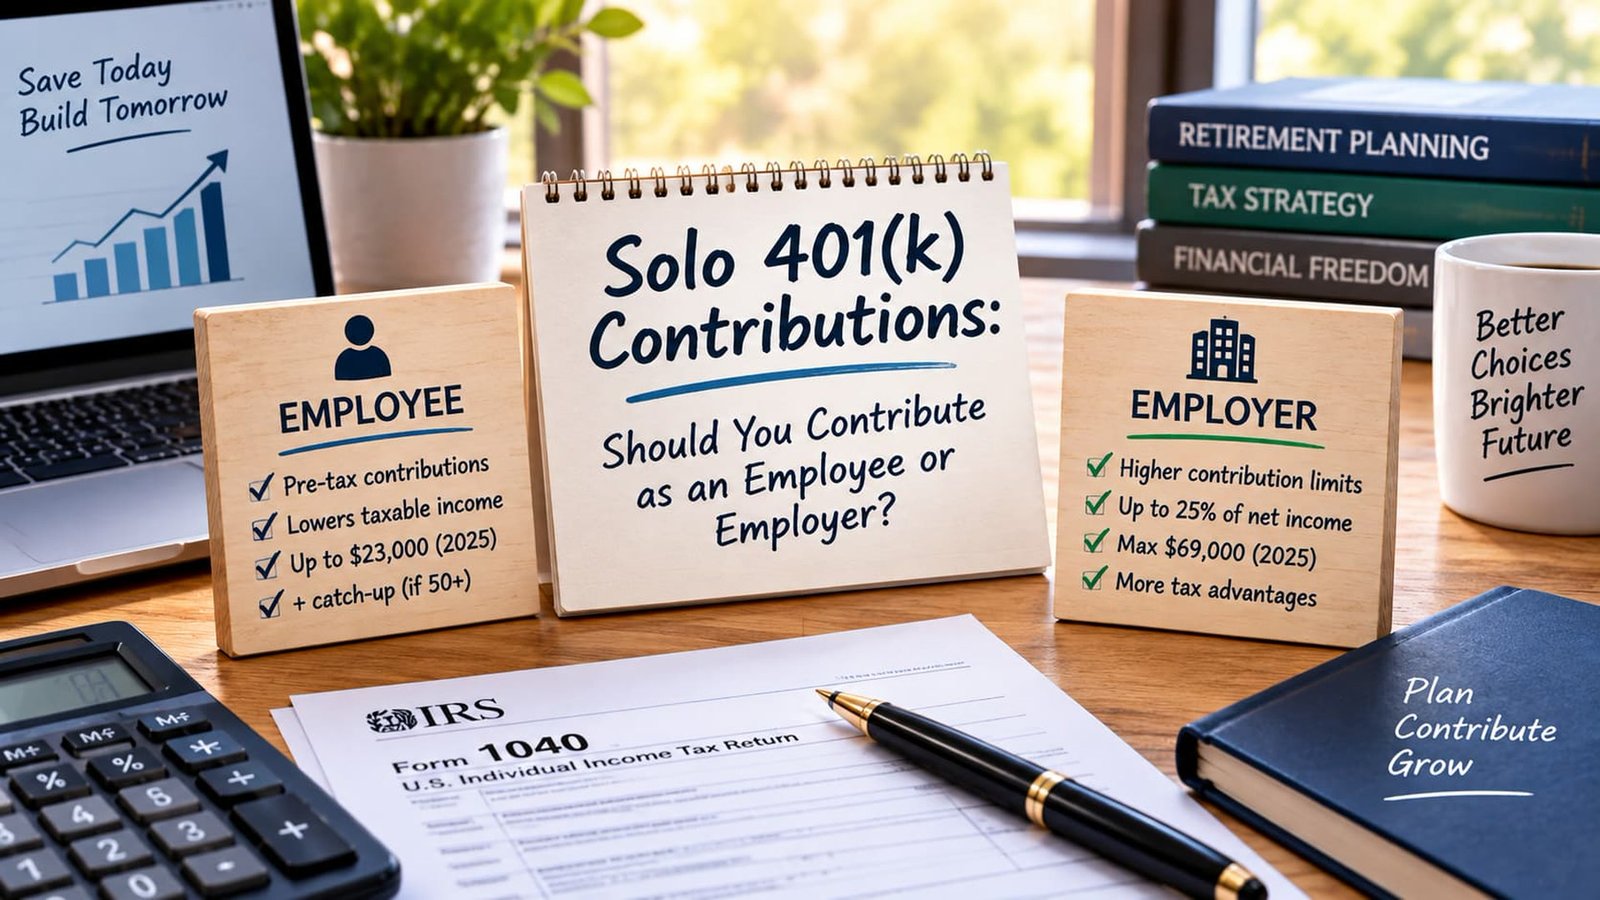
Once you’ve opened a Solo 401(k), the employee deferral is a fixed dollar election — check the current annual limit, since it’s adjusted for inflation each year — that doesn’t depend on how profitable your business was. You can contribute up to that limit as long as you have at least that much in net self-employment earnings, and you choose whether it goes in pre-tax (traditional) or after-tax (Roth), assuming your plan offers both. This flexibility is the main reason the employee side usually gets prioritized first.
The employer side
The employer contribution is a profit-sharing amount, calculated as roughly 20% of your net self-employment earnings after the deduction for half of your SE tax (the same adjusted-profit figure that drives the Self-Employment Tax Calculator‘s numbers). It has to be pre-tax in most plans — no Roth employer contributions are available through most Solo 401(k) providers — and it scales directly with how the business actually performed.
| Employee deferral | Employer profit-share | |
|---|---|---|
| Depends on profit? | No — fixed dollar limit | Yes — % of net earnings |
| Roth available? | Usually | Rarely |
| Best used when | Income is uncertain or early in the year | Profit is known, near year-end |
A worked example
Suppose your net self-employment earnings after the SE tax adjustment come to $70,000 for the year. As the employee, you can defer up to the current annual limit, regardless of that $70,000 figure — say, for illustration, $23,000. As the employer, you can then add roughly 20% of $70,000, or about $14,000, on top of that. Combined, you’ve sheltered close to $37,000 from current income tax in a single year — far more than either role could achieve alone, and considerably more than a SEP IRA would allow at the same income level, since a SEP IRA would cap you at the employer-side figure only.
Why order matters
Because the employee deferral doesn’t depend on profit level, it’s the piece you can commit to early — even mid-year, before you know your final numbers — and it’s the only piece that can go into a Roth account if you want tax-free growth instead of a current-year deduction. The employer contribution is better calculated last, once you actually know your net profit for the year, since overcontributing on the employer side is a corrected-excess-contribution headache you don’t want. If your income tends to be back-loaded (a strong Q4), this order also naturally matches when you’ll actually have the cash available to fund each piece.
When to skip the employee side
In a lean cash-flow year, some self-employed filers skip the employee deferral entirely and only make an employer contribution — functionally turning the Solo 401(k) into something closer to a SEP IRA for that year. That’s a completely valid choice; you’re not required to defer anything as an employee just because the plan exists. See Solo 401(k) vs. SEP IRA for how the two compare when you’re weighing which structure fits a variable-income year.
Roth or traditional for the employee side?
This decision deserves its own consideration rather than a default choice. Traditional (pre-tax) deferrals reduce your taxable income this year, which is valuable if you’re in a high bracket now. Roth deferrals give up that current-year deduction in exchange for tax-free growth and tax-free withdrawals in retirement, which tends to favor freelancers earlier in their career, in a lower bracket now than they expect to be in later. There’s no universally correct answer — it depends on your current bracket relative to your expected bracket in retirement.
Putting it together
A common approach: set a modest recurring employee deferral through the year (Roth if you expect to be in a similar or higher bracket later), then calculate the employer contribution once your Schedule C is finalized. Run the resulting deduction through the Tax Deduction Calculator to see how it changes what you actually owe before you file.
What happens if you contribute too much
Overcontributing to either side of a Solo 401(k) creates a genuine problem: excess contributions generally need to be withdrawn (along with any earnings on them) before your tax filing deadline to avoid additional penalty taxes. This is exactly why the employer contribution is best calculated last, after your Schedule C is finalized — estimating it mid-year based on a profit projection that doesn’t pan out is the most common way freelancers accidentally overcontribute. If you do discover an excess contribution, most plan providers have a standard process for correcting it, but it’s far easier to avoid the situation than to fix it after the fact.
How self-employment tax interacts with your contribution
It’s worth being clear about what a Solo 401(k) contribution does and doesn’t affect. Both the employee and employer contributions reduce your income tax, but neither reduces your self-employment tax — the 15.3% SE tax calculated on Schedule SE is based on your net profit before retirement contributions come off. See the Social Security tax guide for the full mechanics of that separate calculation, so you’re not surprised that a large retirement contribution doesn’t lower your SE tax bill the way it lowers your income tax bill.
A note on timing your contributions through the year
Nothing requires you to contribute in one lump sum. Many self-employed filers set up recurring monthly or quarterly employee deferrals timed to when income actually arrives, rather than trying to fund the whole year’s contribution at once near the deadline. This spreads out the cash-flow impact and reduces the temptation to skip retirement saving entirely in a year that starts slow but improves later — a habit that tends to result in more consistent long-term saving than an all-or-nothing approach calculated once a year.
Comparing this to a traditional 401(k) from a past job
If you previously had a 401(k) through an employer, the Solo 401(k)’s structure will feel familiar in some ways and different in others. The core concept — pre-tax or Roth elective deferrals, an annual contribution limit — carries over directly. What’s different is that you’re now also the “employer” deciding on the profit-sharing contribution, a decision that used to be made entirely by your employer’s HR or finance department according to a fixed plan formula. This added control is a genuine advantage of self-employment, but it also means more responsibility to calculate it correctly and fund it within the required deadlines each year, rather than having it happen automatically through payroll.
What to do with an old 401(k) from a previous employer
Many new business owners have an existing 401(k) balance sitting with a former employer’s plan administrator. This doesn’t need to be combined with your new Solo 401(k) immediately, but it’s worth reviewing: some Solo 401(k) providers accept rollovers from prior employer plans, which can simplify account management and, in some cases, unlock a loan feature against the combined balance that wasn’t available while the funds sat with the old employer’s plan. This is a decision worth making deliberately rather than leaving an old account on autopilot indefinitely, particularly if the old plan’s investment options or fees aren’t competitive with what’s available to you now.
Bottom line
Treating the employee and employer sides as two separate decisions — one flexible and ongoing, one calculated once you know your final numbers — gets you the most out of a Solo 401(k) without the risk of overcontributing on either side.
Related guides
- Take-Home Pay Calculator
- How to Avoid Self-Employment Tax Legally: 9 Strategies That Work
- What Counts Toward Your AGI When You’re Self-Employed
- Self-Employed Tax Deductions: The Complete List for 2026
- Can Gig Workers Claim the QBI Deduction Without an LLC or Sole Proprietorship?
- Freelance Graphic Designer Tax Deductions: Software, Hardware, and Home Studio Costs
- Freelance Web Developer and Web Designer Tax Deductions: Software, Hosting, Coworking, and Gear
- Freelance Photographer Tax Write-Offs: Gear, Depreciation, Travel, and Studio Costs
- How Much Tax Do You Pay on a 401(k) or IRA Withdrawal? Worked Examples by Age
- Inherited 401(k) Taxes: The 10-Year Rule, RMDs, and What a Beneficiary Owes
- How Much Does a 401(k) Contribution Reduce Your Taxes? The Deduction Math With Examples
- Roth Conversion Taxes: How to Estimate the Bill and Report It on Form 8606